Kala
Turning lenders into fintechs.
I joined as a founding member, right after Kala’s first funding round, and helped build it from scratch side by side with the CEOs, the VP of Product and the VP of Engineering.
The challenge
Many lenders in Latin America still ran credit in person: branch visits, paper documents and days of waiting for an answer.
Kala gives financial institutions the technology to digitize the whole credit experience, from the first application to the final decision.
The goal: help them become a fintech quickly and easily, without building it themselves.
Who we designed for
- Credit analysts reviewing applications
- Teams with their own offices, roles and approval rules
- Need speed without losing control
- Used to in-person processes
- Want a clear, fast answer
- Expect a simple digital experience
0 → 1 · Credit, fully digital
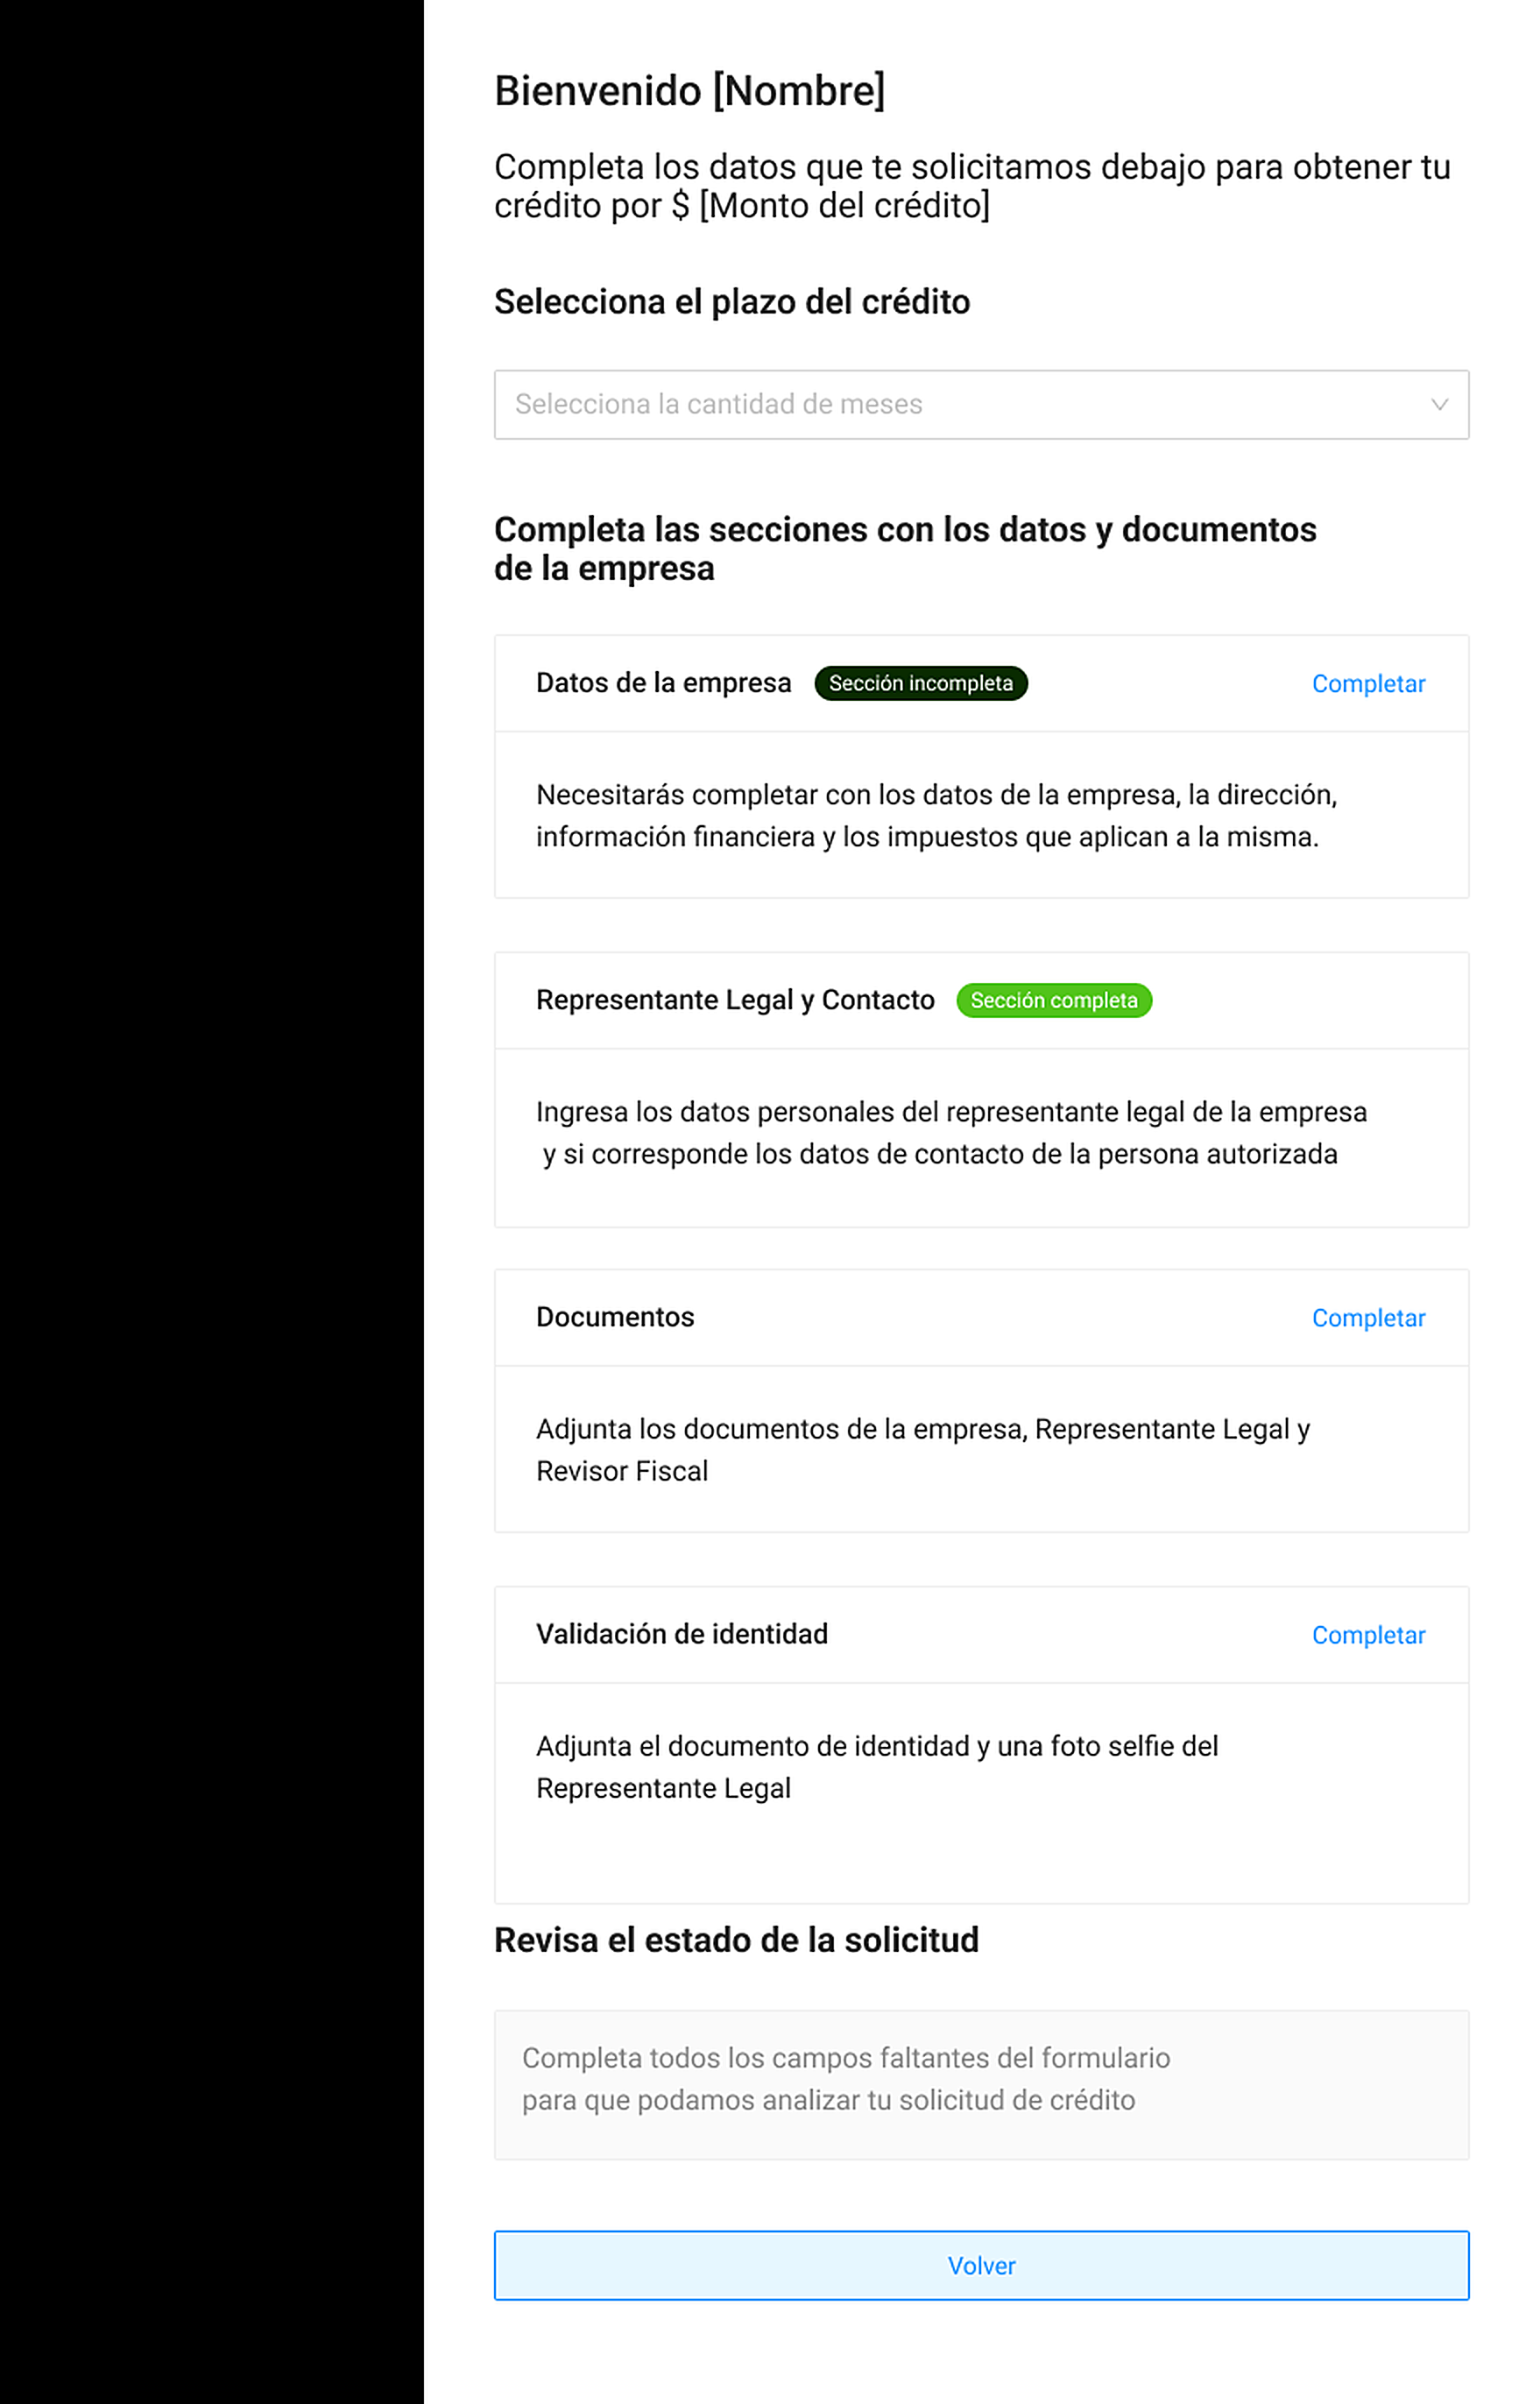
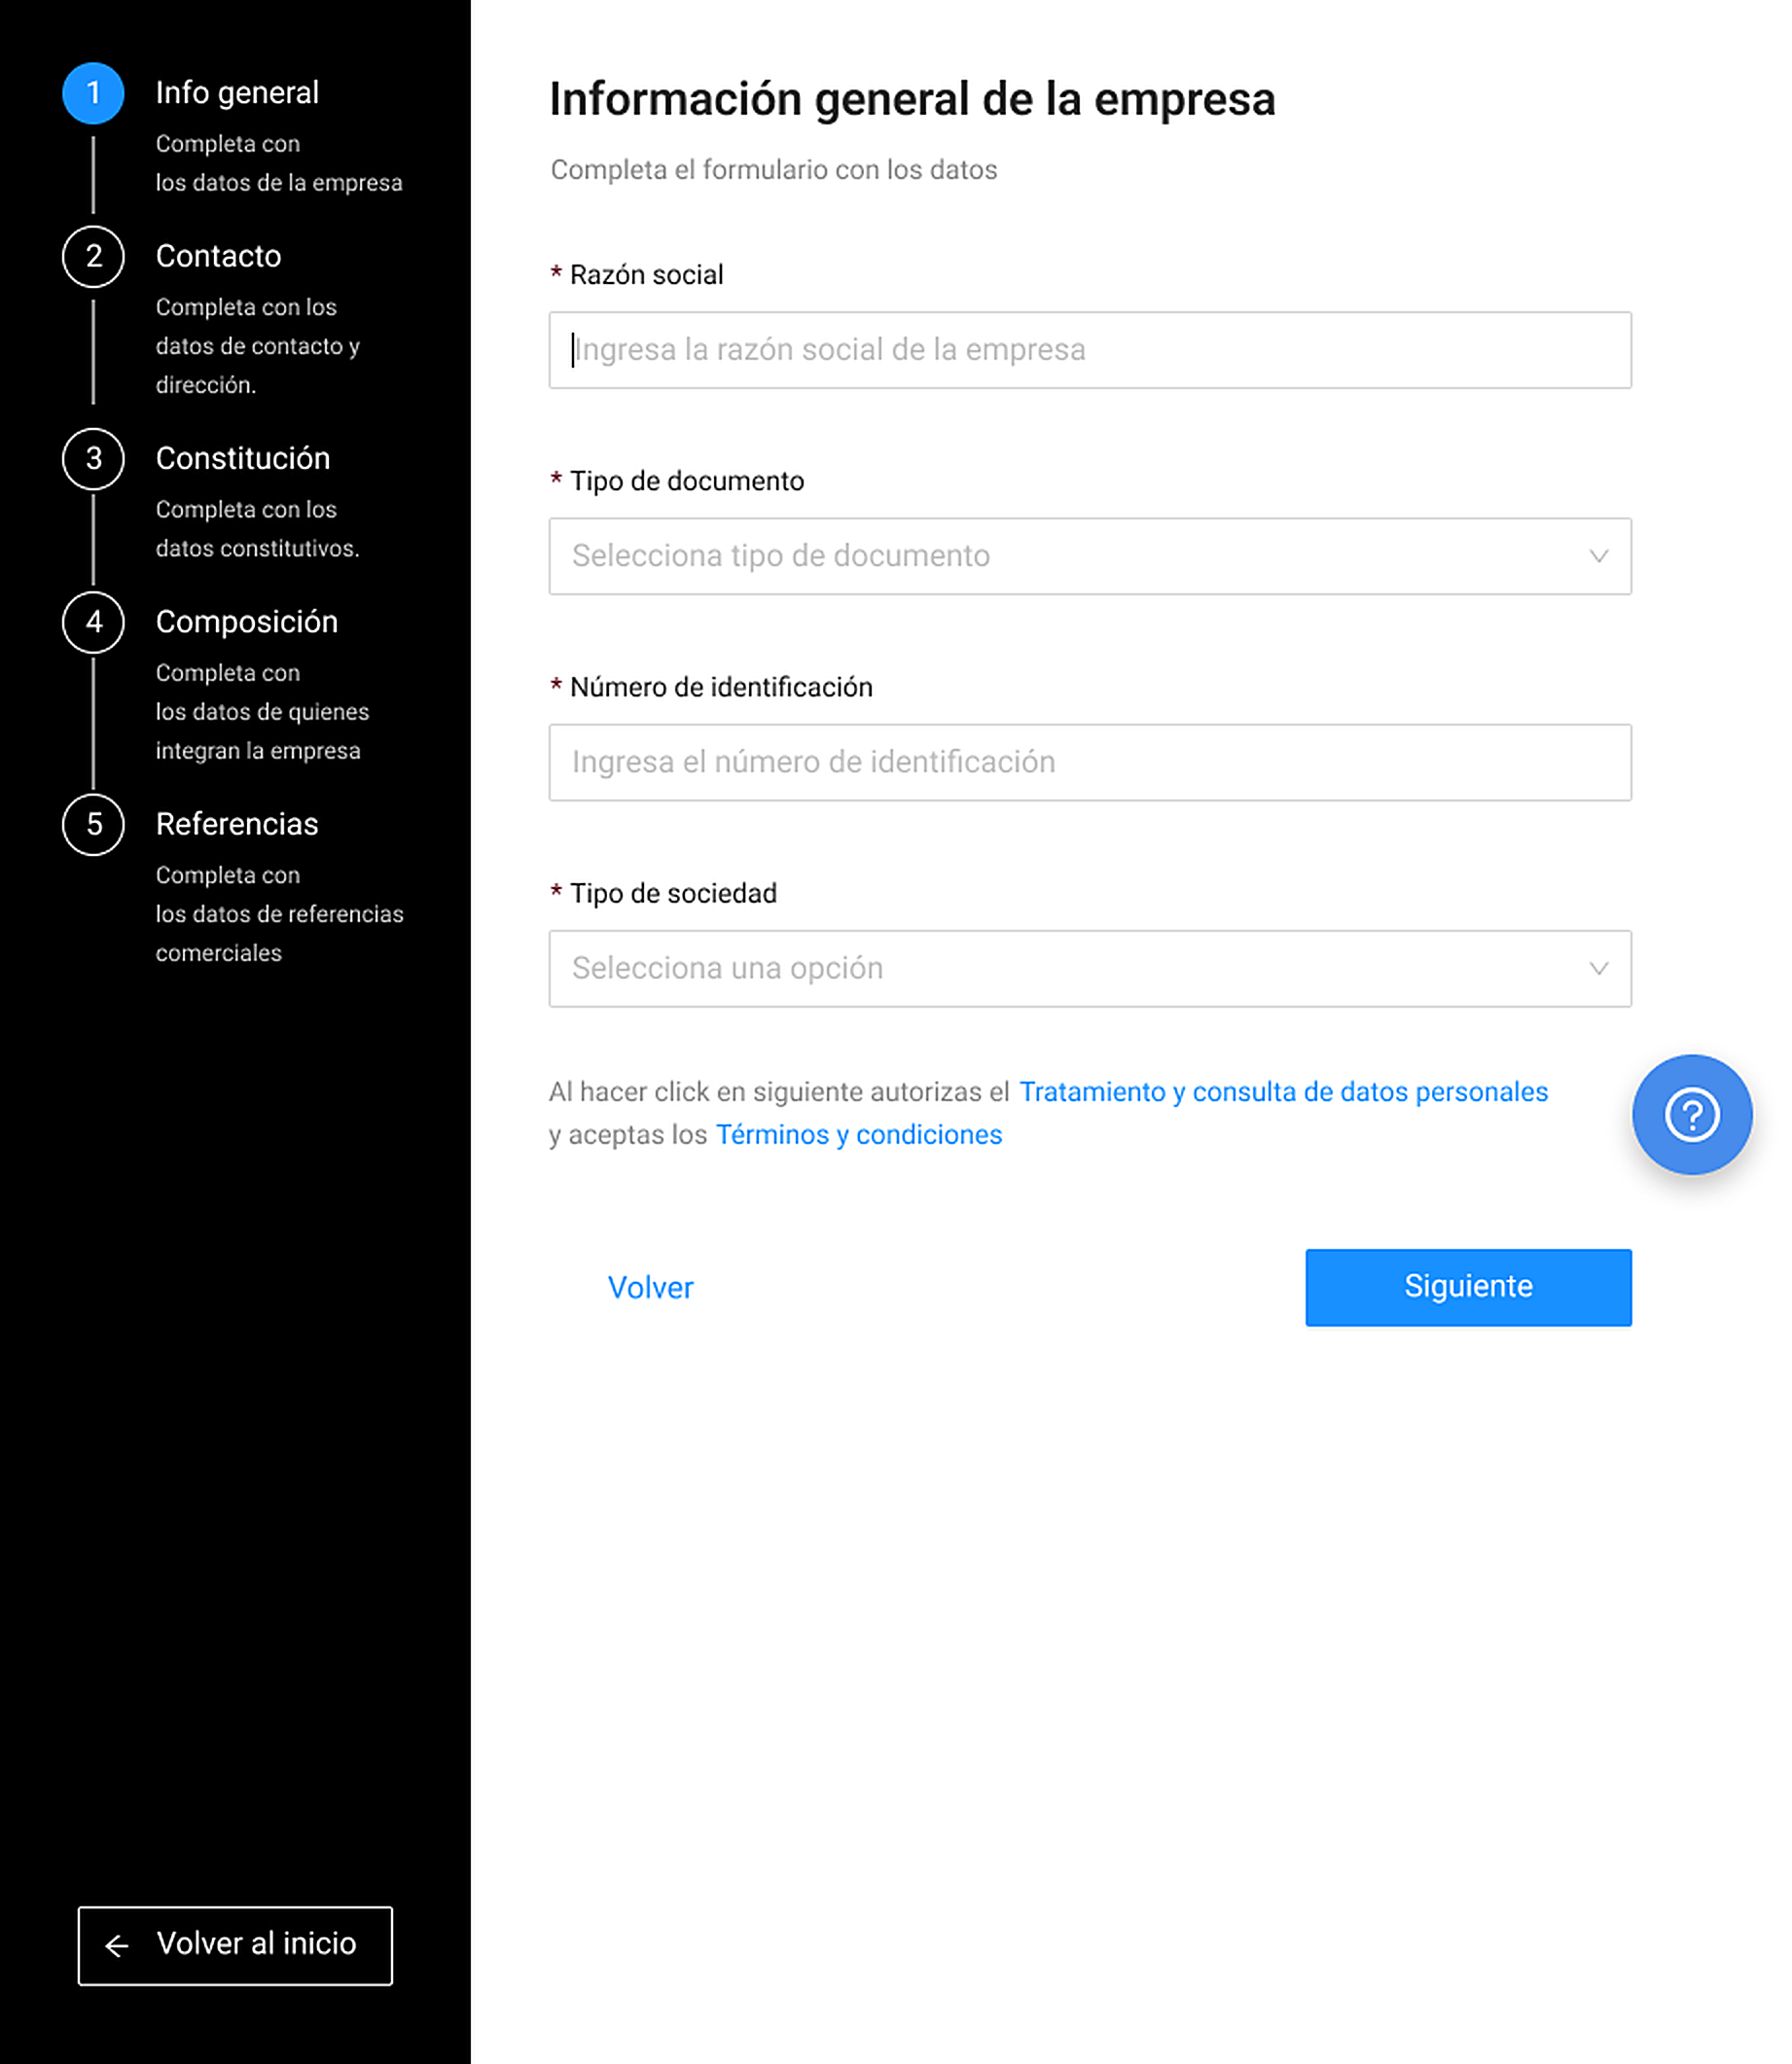
We replaced in-person steps with a white-label credit application that each institution can customize with its own brand and requirements.
Inside the application, everything is split into clear sections, so people always know what’s done, what’s missing and what comes next.
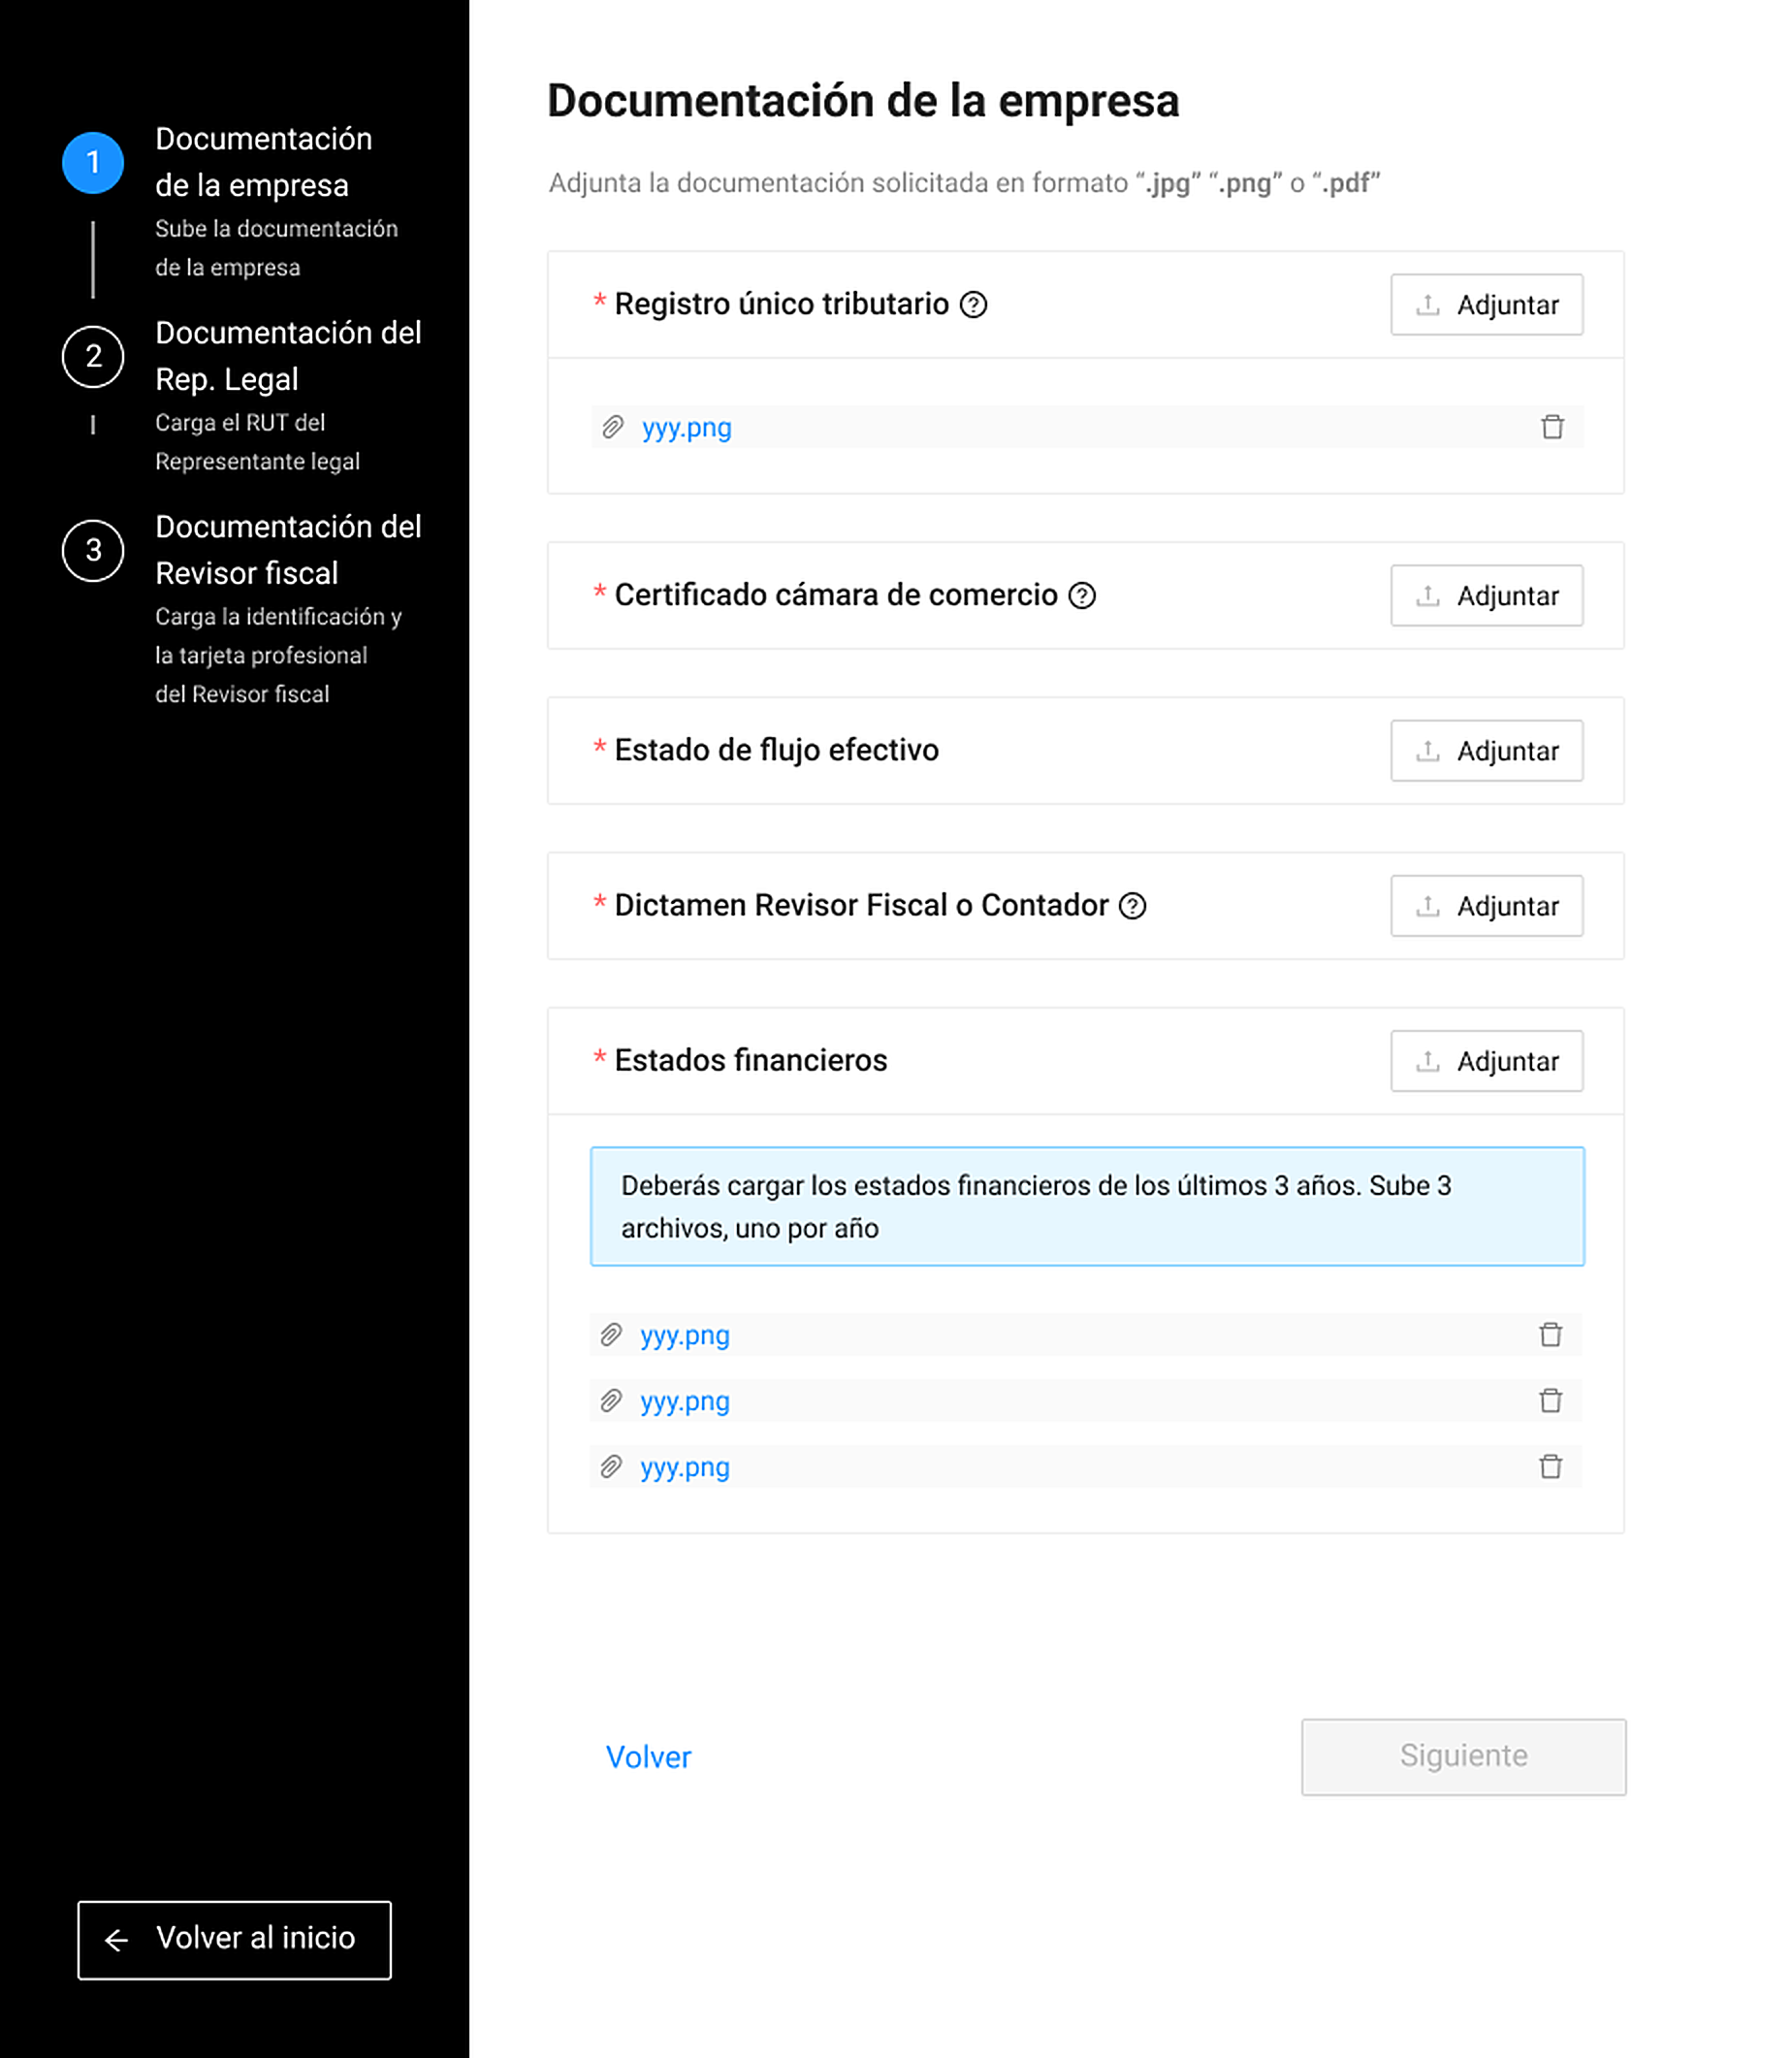
Processing time for our clients, from 7 business days to 2 hours.
One place to decide
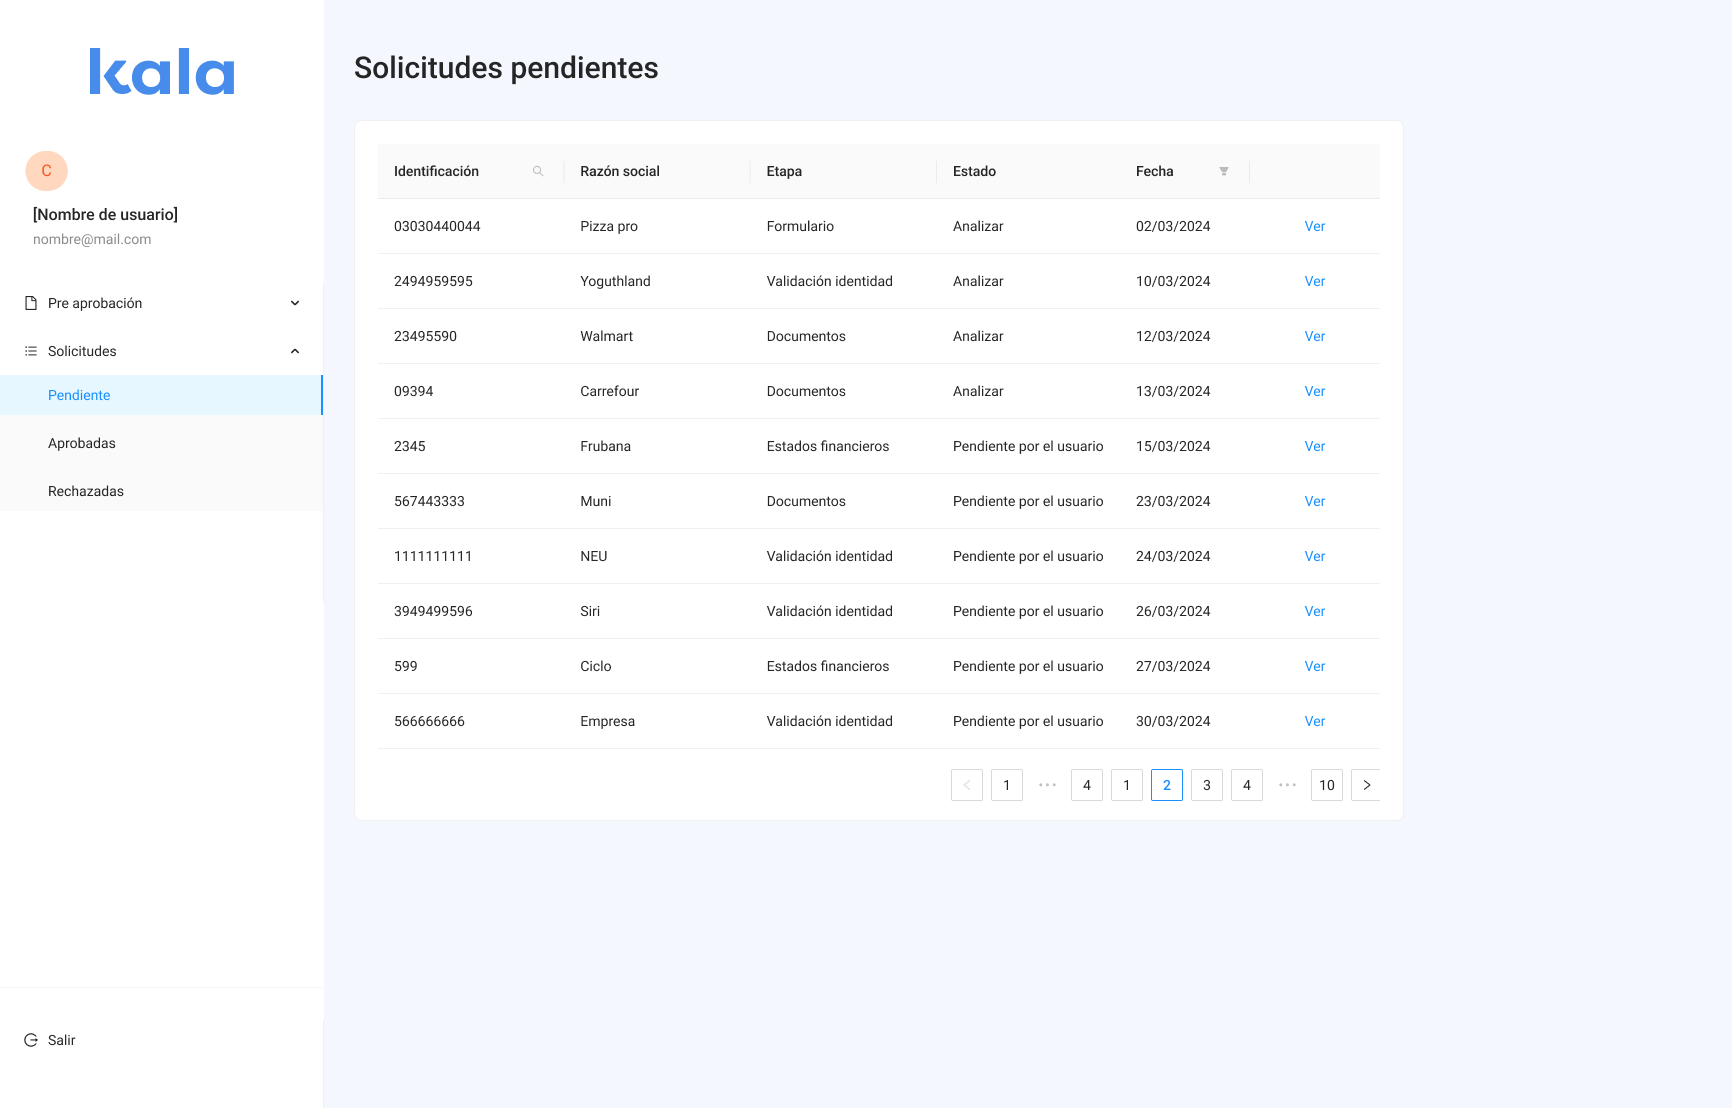
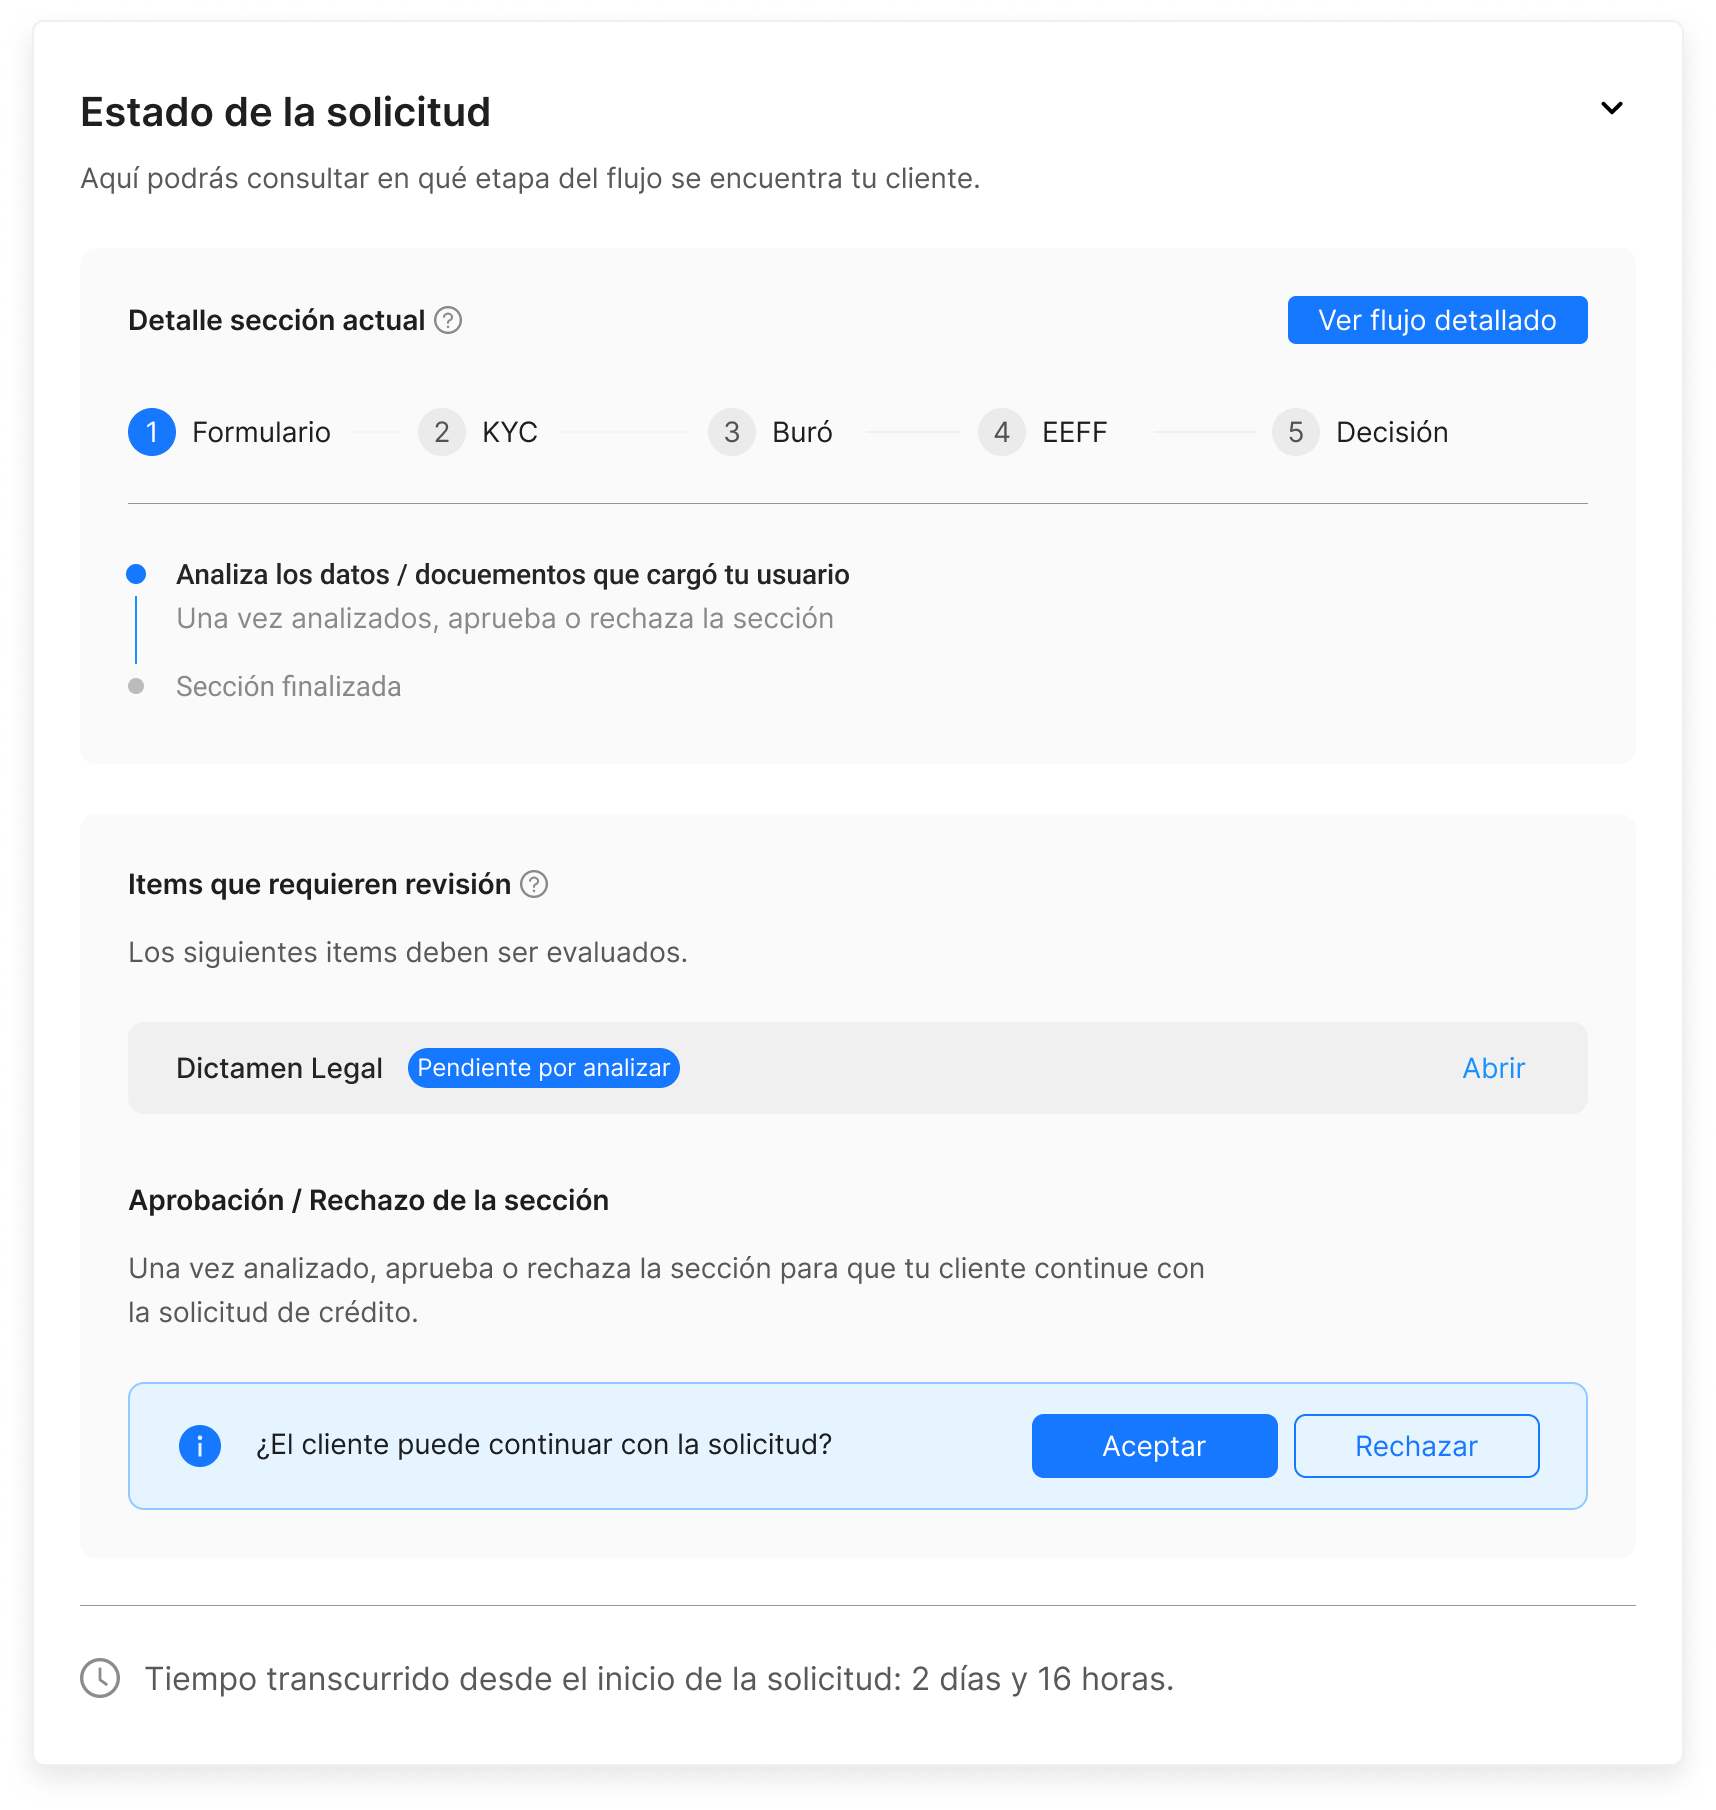
Once people apply, institutions get everything in the application manager: applicant data, uploaded documents and information from external sources.
Built for how each lender works
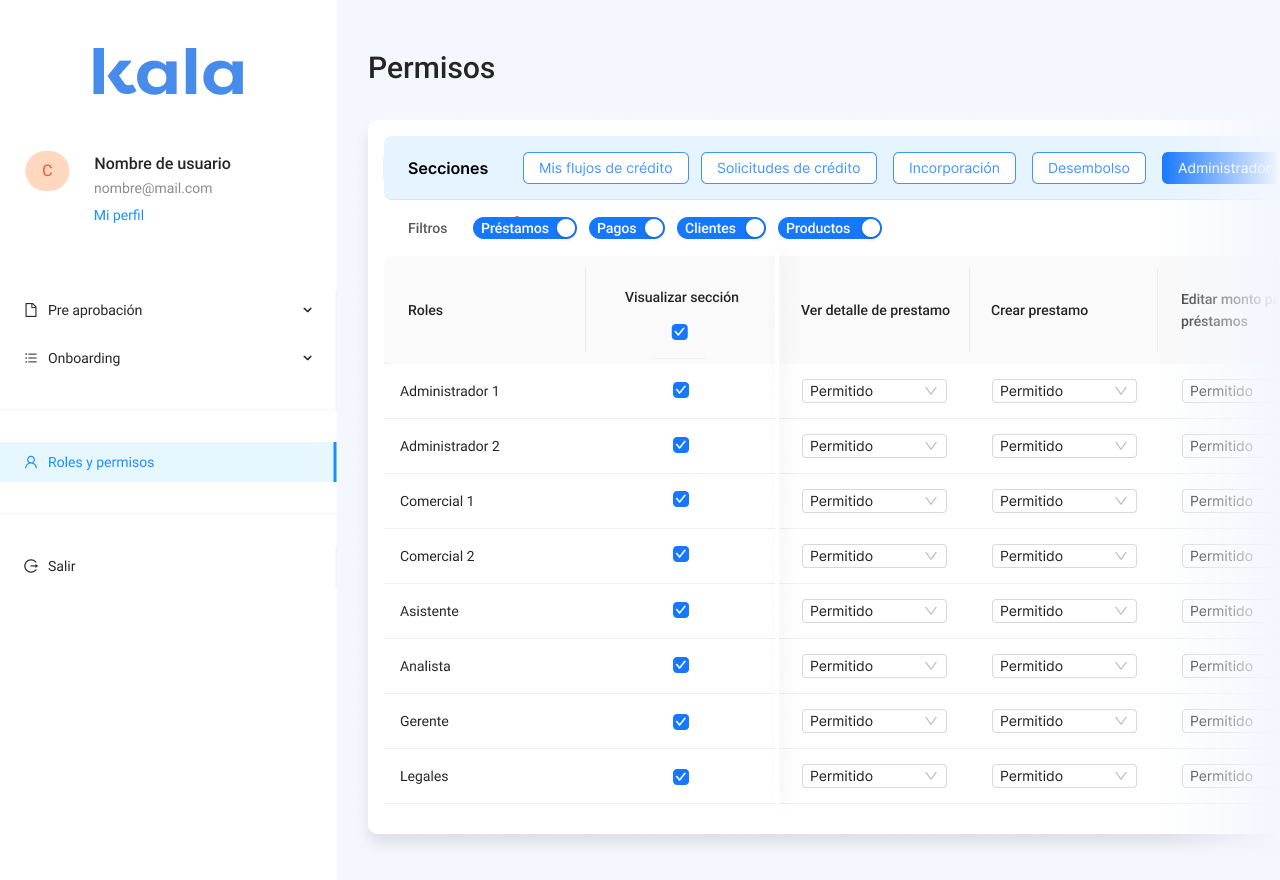
Every institution has its own offices, roles and permissions.
So the admin tool includes a fully customizable roles and permissions section, where each institution decides who can see and do what on each credit application.
1 → scale · Dynamic credit workflows
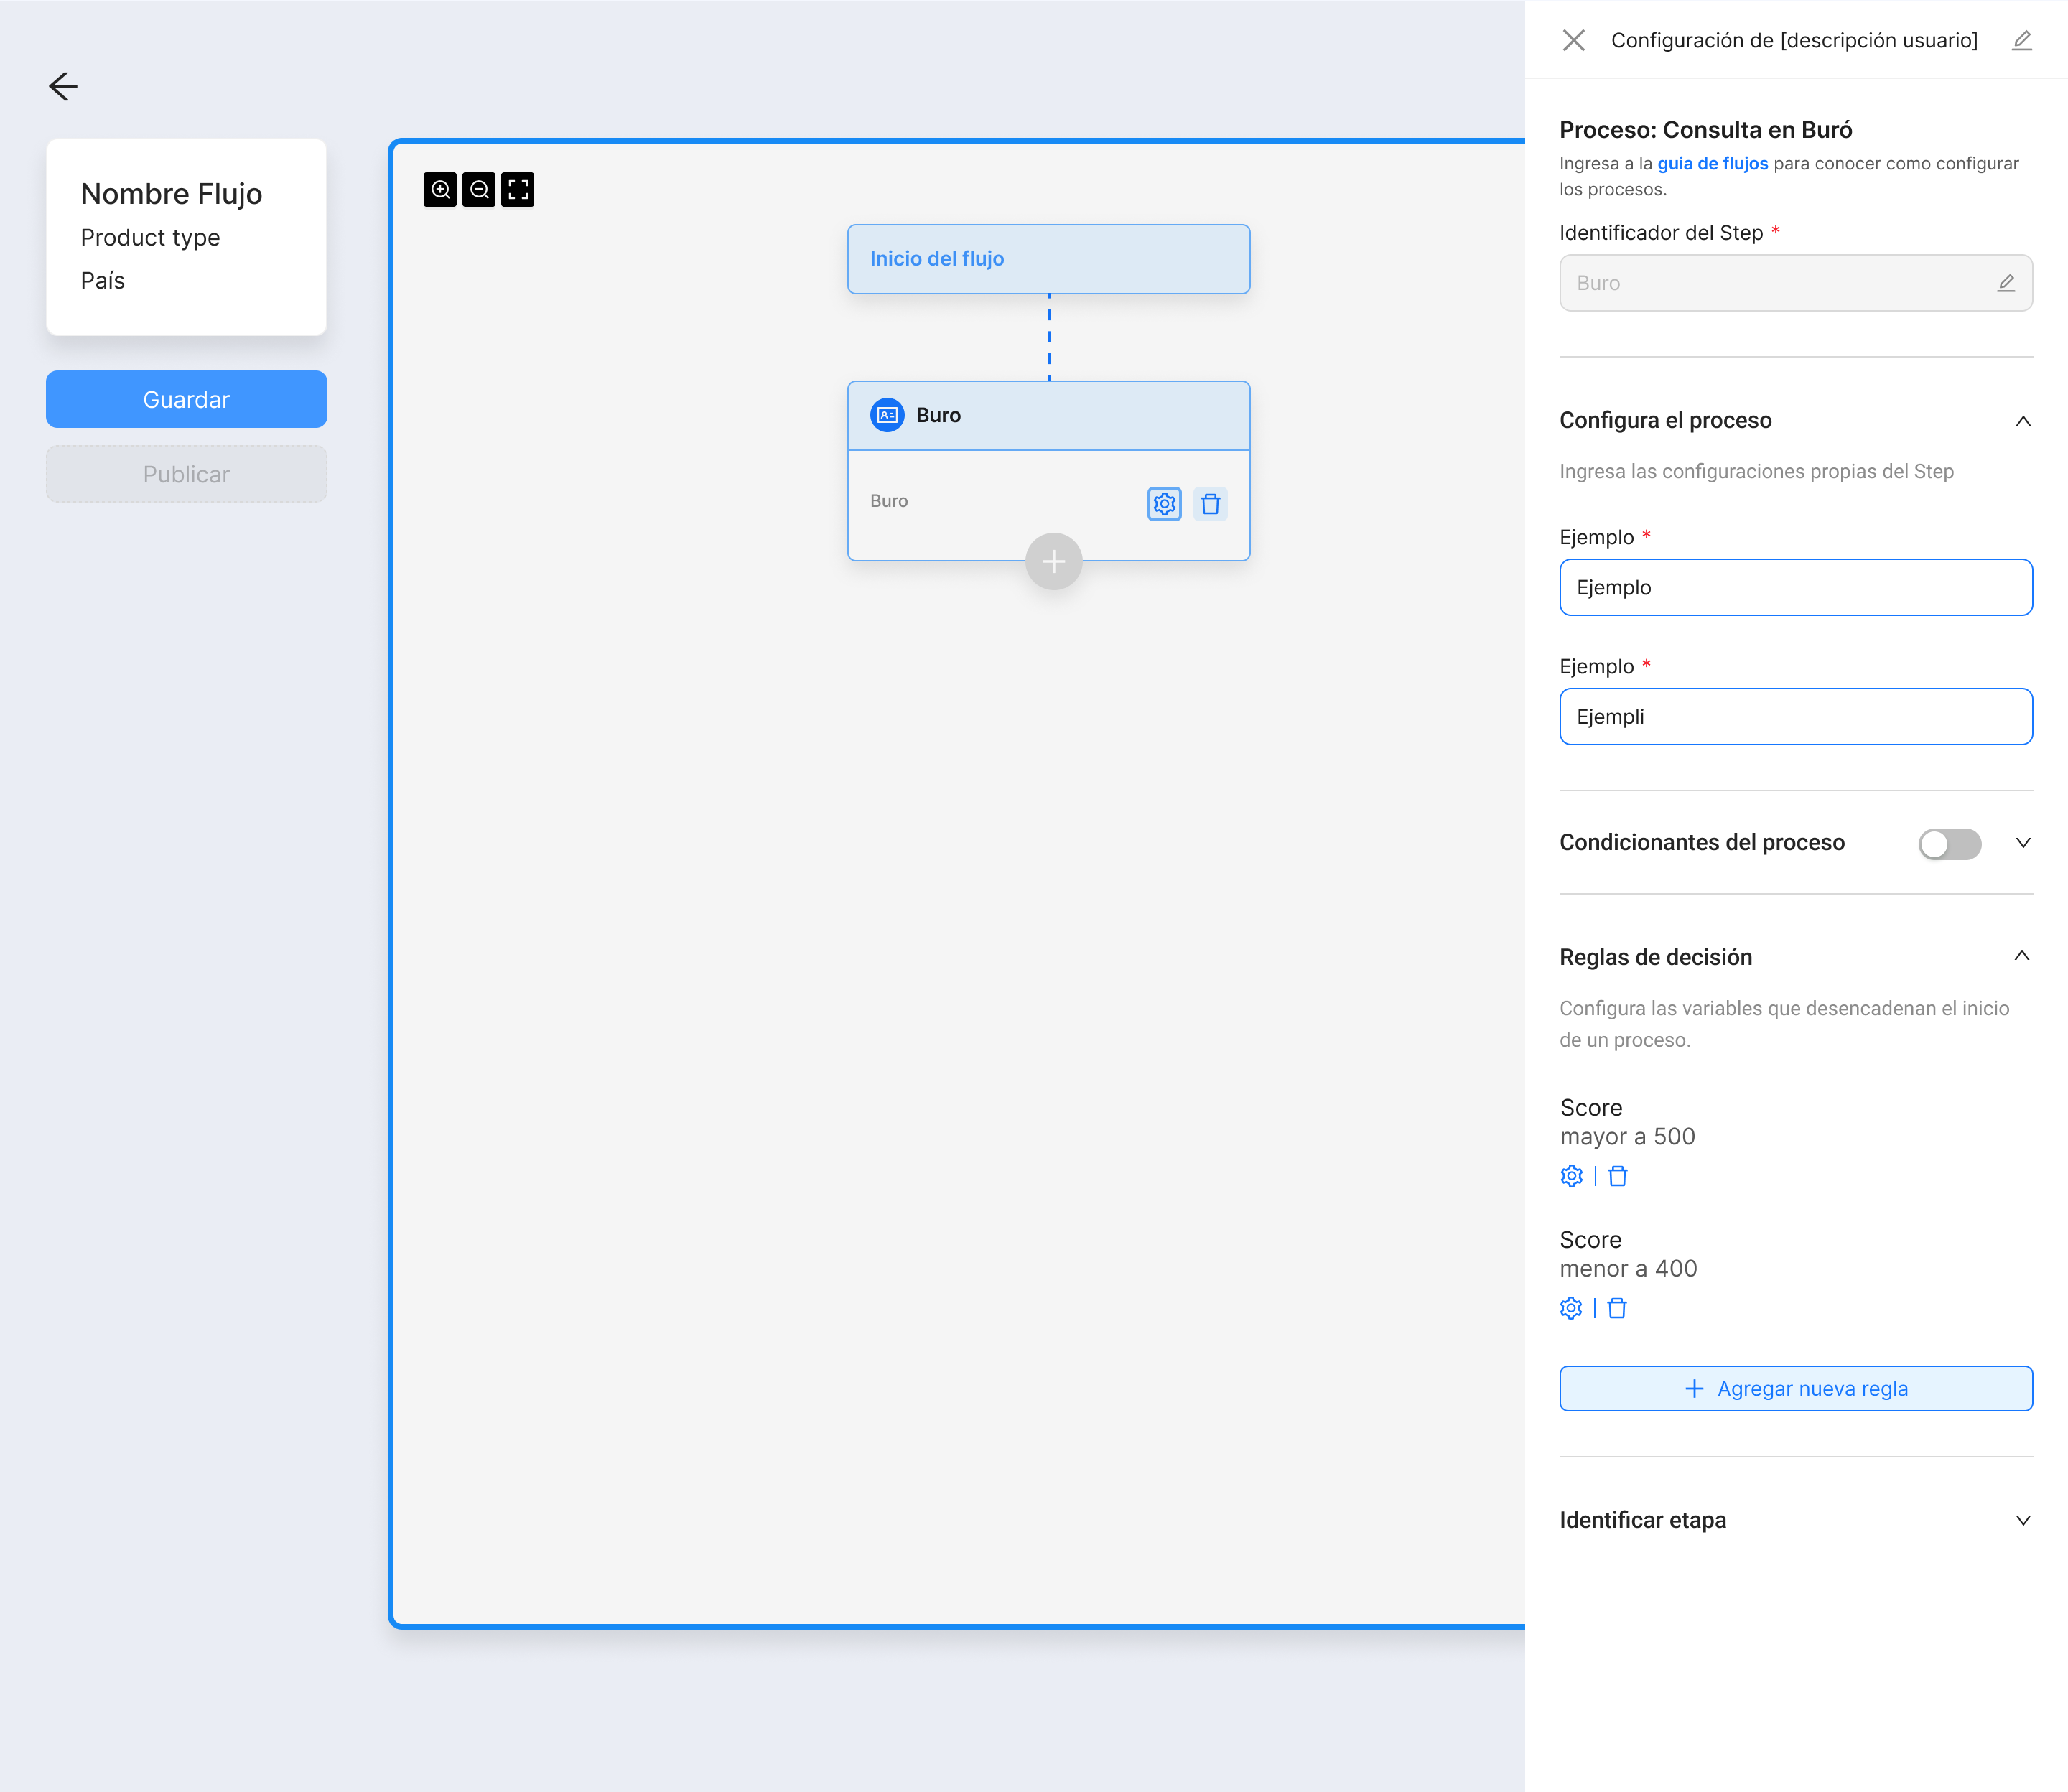
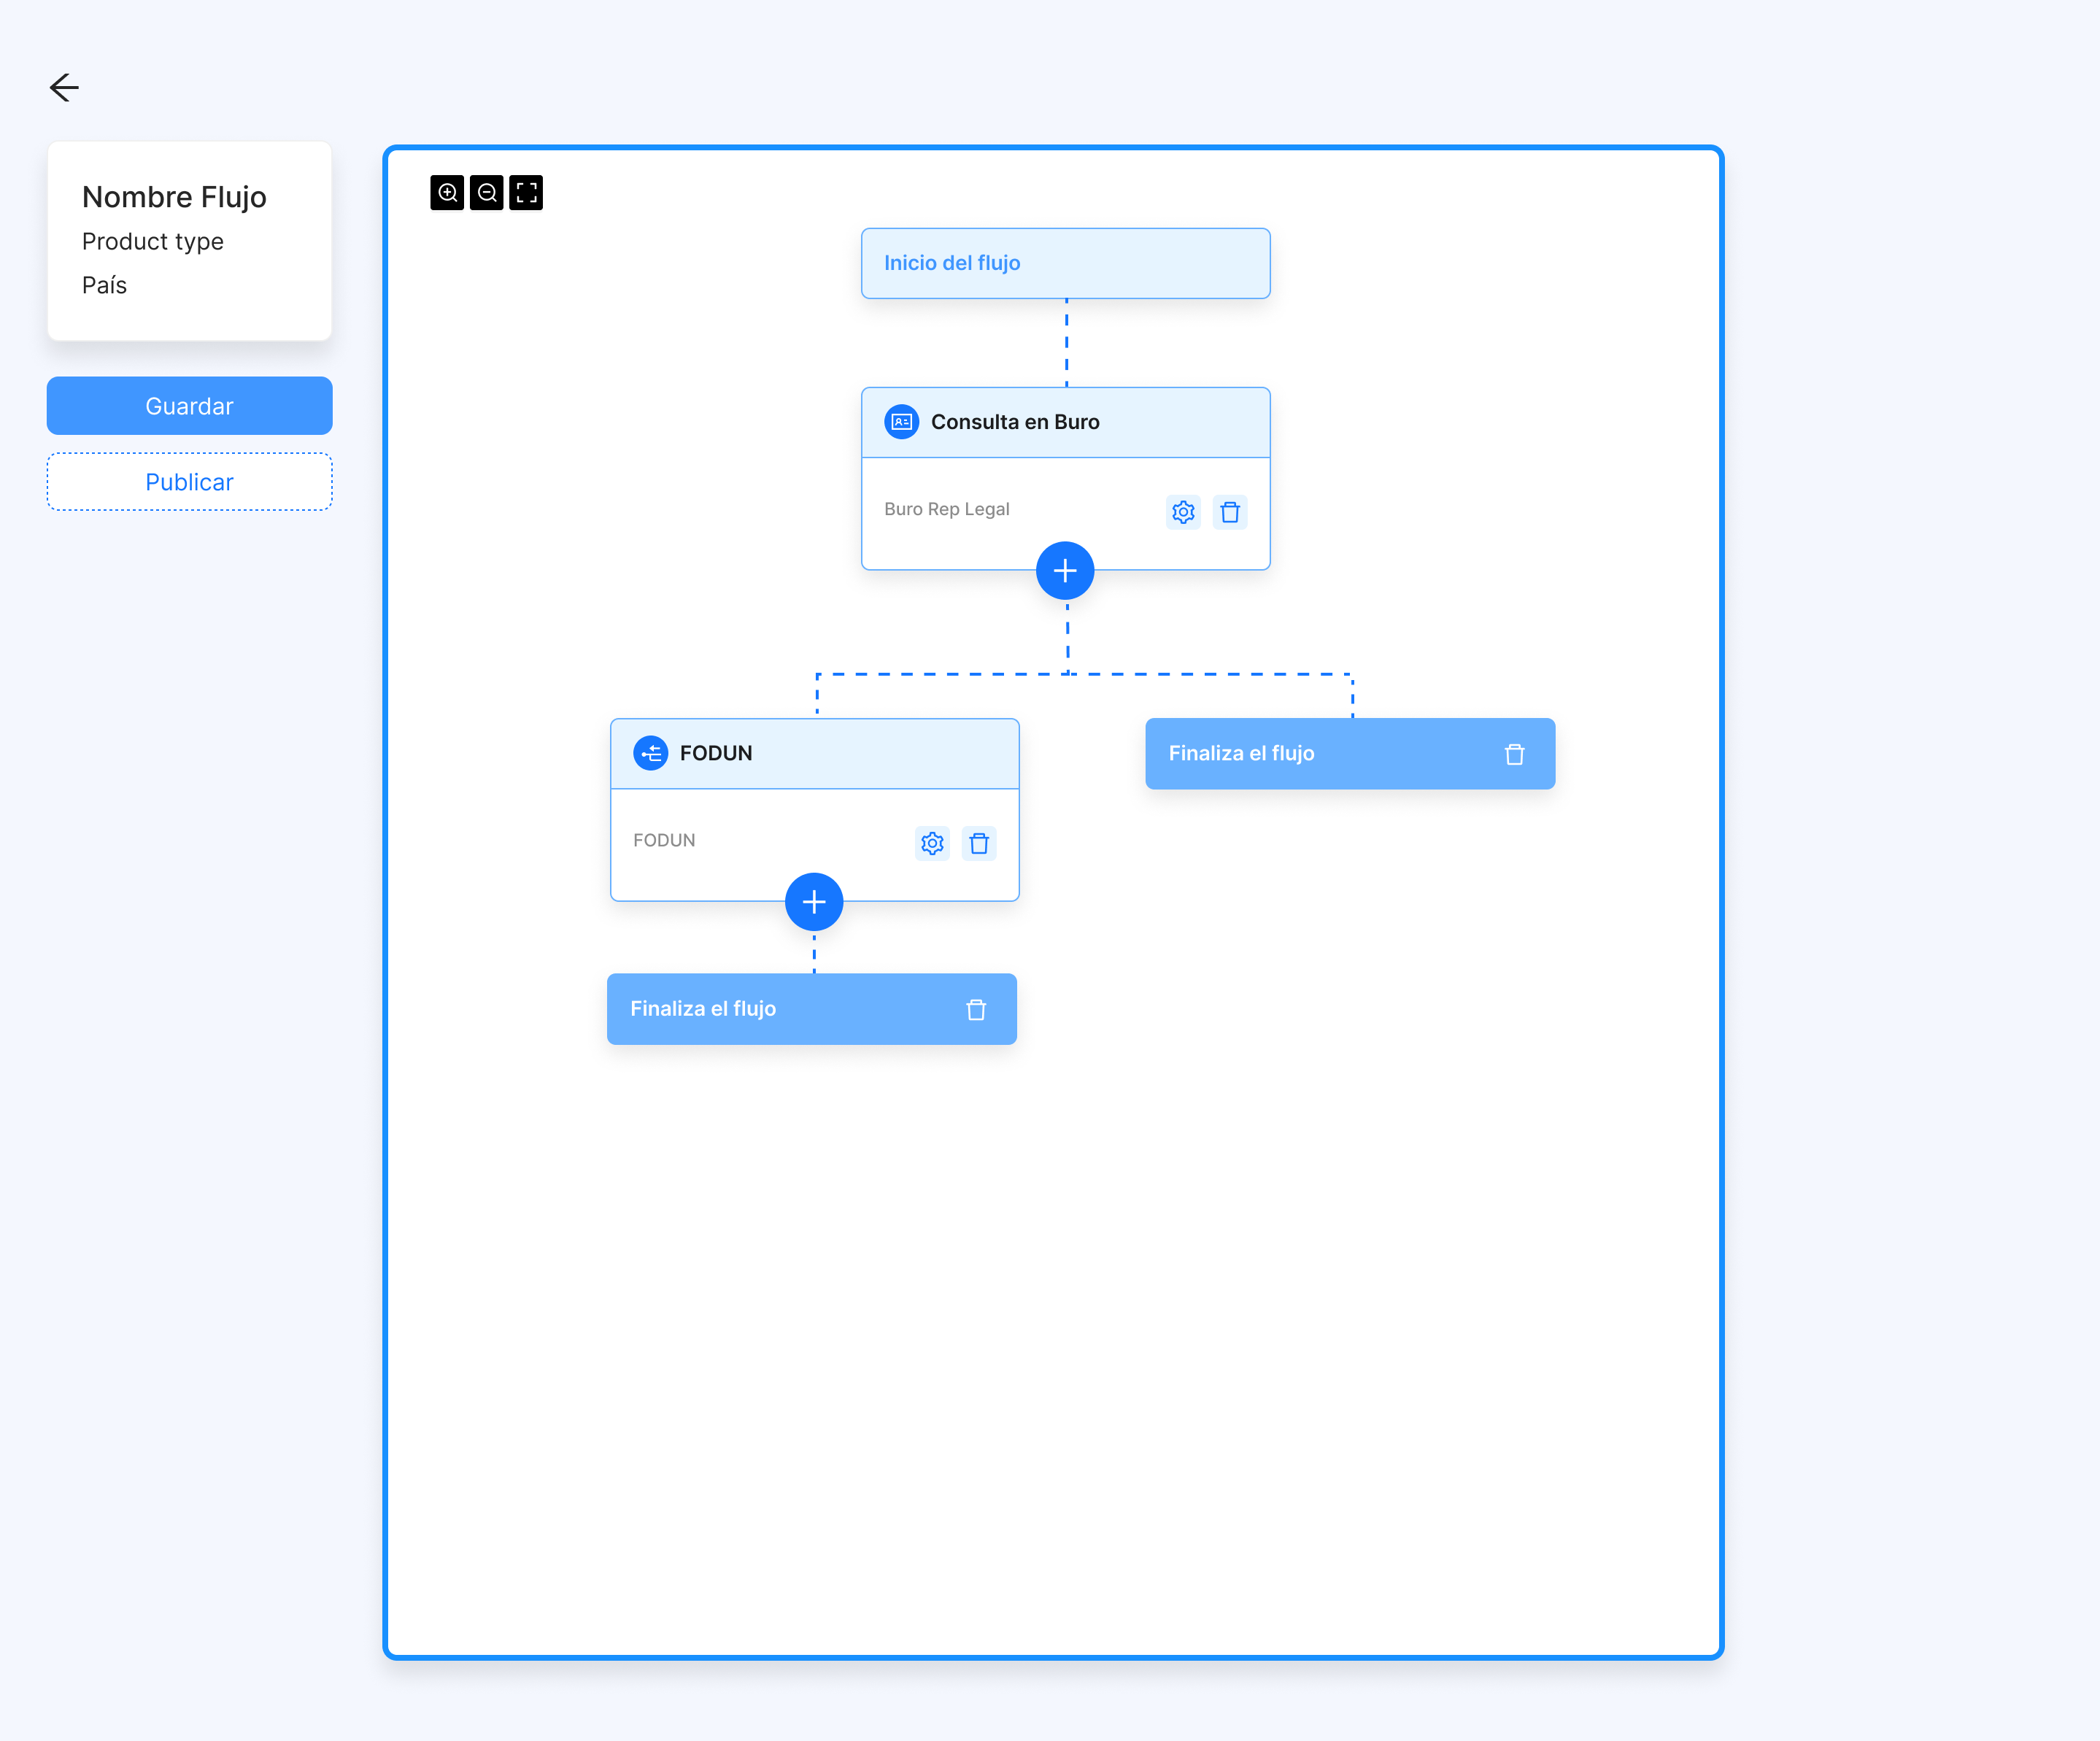
No two lenders work the same way, so no two forms should either. We started exploring a builder where each institution creates its own credit flows, with rules that react to external data.
For example: if a person’s score is above a threshold, they move on to identity verification; if not, another provider is queried for more information.